Introduction
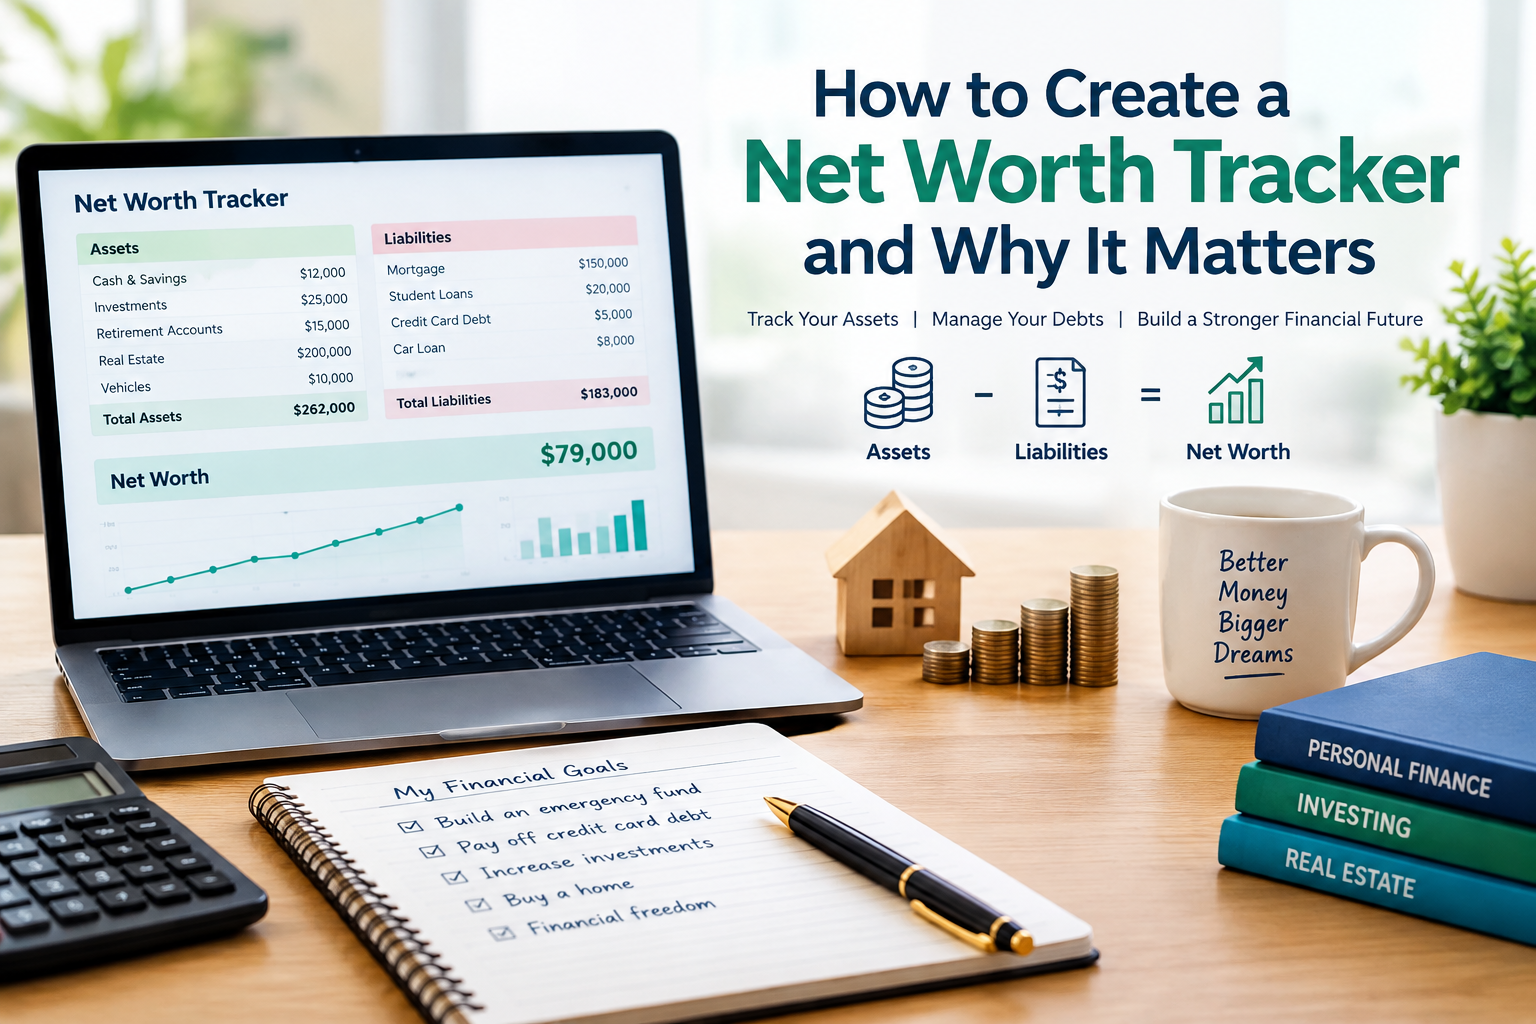
Managing money becomes easier when you understand what you own and what you owe. You might earn a regular income and save money every month. However, without a clear financial picture, it can be difficult to know whether your overall financial position is improving. A Worth Tracker can help you organize your finances and measure your progress over time.
Many people focus only on their monthly income or bank balance. These figures matter, but they do not tell the whole story. You may have money in savings and investments while also carrying credit card balances or a home loan. Understanding both sides gives you a more complete view of your financial health.
A Worth Tracker provides a simple way to record your assets and debts in one place. You can use a spreadsheet, a notebook, or a digital tool to calculate your net worth and review changes over time. This guide explains how to create one, what information to include, and how to use it to make more informed financial decisions.
What Is a Worth Tracker?
A Worth Tracker is a personal finance record that helps you monitor the value of your assets compared with your outstanding liabilities. Its main purpose is to show your net worth at a particular point in time and help you understand how that figure changes.
Your net worth is calculated using a straightforward formula:
\[ \text{Net Worth}=\text{Total Assets}-\text{Total Liabilities} \]
Assets are things you own that have financial value. They may include cash, savings, investments, retirement accounts, vehicles, and property. Liabilities are amounts you owe, such as credit card balances, personal loans, student loans, and mortgages.
For example, imagine your assets total $45,000 while your outstanding debts total $18,000. Your net worth would be $27,000. This figure is a snapshot of your financial position rather than the amount of cash you can immediately spend. A useful Worth Tracker records these values consistently so you can compare your position across different months or years.
Why Does a Worth Tracker Matter?
It Shows Your Overall Financial Position
Your bank balance alone cannot tell you how financially secure you are. You might have $5,000 in savings but owe $12,000 on a personal loan. Looking at both assets and liabilities helps you understand the broader picture.
A Worth Tracker brings this information together. It can reveal whether your debts are becoming smaller, your savings are increasing, or your investments are changing in value.
It Helps You Set Realistic Financial Goals
Financial goals become easier to plan when you know your starting point. You might want to build an emergency fund, reduce debt, save for a home deposit, or prepare for retirement.
A Worth Tracker gives you a baseline against which to measure progress. You can set achievable targets and adjust them when your income, expenses or personal circumstances change.
It Encourages Better Money Habits
Regular reviews can help you notice patterns that might otherwise go unnoticed. For example, you may discover that rising credit card balances are offsetting the money you have recently saved.
Seeing these changes can encourage more thoughtful spending and consistent saving. However, tracking alone does not improve finances. The real benefit comes from using the information to make sensible decisions.
It Helps You Measure Long-Term Progress
Your financial position can change because of saving, debt repayment, investment performance, property prices and other factors. A Worth Tracker helps you record these changes instead of relying on memory.
The goal is not necessarily to see your net worth increase every month. Short-term declines can occur even when you follow a reasonable financial plan. What matters is understanding the reasons behind those changes and reviewing your progress over an appropriate period.
How to Create a Worth Tracker Step by Step
Creating a Worth Tracker does not require advanced financial knowledge or expensive software. You can start with a basic spreadsheet and update it whenever you review your finances.
Step 1: Choose Your Tracking Method
First, decide where you want to record your financial information. A spreadsheet works well if you want control over your figures and calculations. A notebook may suit someone who prefers writing things down, while a reputable financial app may offer automatic account updates.
Choose a method that you can maintain consistently. A Worth Tracker is only useful when the information is reasonably accurate and updated regularly. If you use an app, review its privacy policy, security features, and data-sharing practices before connecting financial accounts.
Step 2: List All Your Assets
Make a complete list of the assets you own. Use current and reasonable estimates rather than the original purchase prices.
Common assets include:
- Cash and bank savings.
- Stocks, bonds and mutual funds.
- Retirement accounts and other investments.
- Your home or other real estate.
- Vehicles and other valuable possessions.
Record the estimated value of each item. For investments and property, values may change over time. A Worth Tracker should reflect reasonable current estimates rather than assume that prices remain fixed. Avoid counting the same money twice. For example, if your investment account balance already includes cash held inside that account, do not list that cash again as a separate asset.
Step 3: Record All Outstanding Debts
Next, list your liabilities. Include credit card balances, personal loans, student loans, car finance, mortgages, and other outstanding obligations. Use the amount you currently owe rather than the original loan amount. This gives your Worth Tracker a more accurate picture of your present financial position.
Remember that a home with a mortgage contributes both an asset and a liability. You should include the estimated market value of the property under assets and the remaining mortgage balance under liabilities. The difference contributes to your net worth.
Step 4: Calculate Your Net Worth
Add the value of all assets and then add the balances of all liabilities. Subtract the second total from the first. Here is a hypothetical example of how a Worth Tracker might look.
| Financial item | Amount |
|---|---|
| Cash and savings | $8,000 |
| Investments | $12,000 |
| Vehicle value | $10,000 |
| Home equity assets before mortgage | $0 |
| Total assets | $30,000 |
| Credit card debt | $2,000 |
| Car loan | $6,000 |
| Student loan | $4,000 |
| Total liabilities | $12,000 |
| Net worth | $18,000 |
This example assumes the person does not own a home and has no other assets or debts. The vehicle is valued at its estimated current resale value. The calculation is $30,000 minus $12,000, giving a net worth of $18,000. You can use the same method in your own Worth Tracker regardless of the currency you use.
Step 5: Set Financial Goals
After calculating your starting figure, identify what you want to improve. Your goal could be to reduce expensive debt, increase emergency savings, or build investments for a long-term objective.
A Worth Tracker helps you connect these goals to measurable changes. For instance, you could aim to reduce a credit card balance by a set amount over six months while maintaining enough savings for essential expenses. Keep your targets realistic. Do not take unnecessary financial risks or neglect essential bills just to increase your net worth faster.
Step 6: Update Your Records Regularly
Choose a schedule that suits your finances. Monthly updates can work well for people with several accounts or active debt repayment plans. A simpler financial situation may only require quarterly reviews, with a more complete annual review.
Use the same valuation approach each time where possible. A Worth Tracker becomes more useful when you can compare similar figures across different periods. Record the date of each update and make a note of significant changes. This will help you understand why your net worth increased or decreased.
How to Organize Your Worth Tracker
A clear layout makes financial information easier to understand. You can create separate sections for assets, liabilities, totals, and financial goals.
A simple spreadsheet might use these columns:
| Date | Total assets | Total liabilities | Net worth |
|---|---|---|---|
| January | $25,000 | $14,000 | $11,000 |
| February | $26,000 | $13,500 | $12,500 |
| March | $27,000 | $13,000 | $14,000 |
These are illustrative figures rather than a prediction of financial growth. A Worth Tracker can calculate the difference between each month’s totals automatically. In a spreadsheet, the net worth formula can subtract the liabilities cell from the assets cell. You can also add a chart to show the trend over time.
If you maintain multiple accounts or hold assets in different currencies, record the currency and the valuation date. Convert balances consistently if you want a single total. Exchange rates can affect your reported net worth even when the underlying assets have not changed in their original currencies.
Common Mistakes to Avoid
Even a well-designed Worth Tracker can produce misleading results if you enter incomplete or inaccurate information. Avoid these common mistakes when managing your records.
Forgetting Small Debts and Expenses
Small balances can add up. Unpaid credit card amounts, personal loans and other outstanding obligations should be included. Leaving out debts can make your financial position appear stronger than it really is.
Overestimating Asset Values
An item’s original price does not necessarily reflect what it is worth today. Vehicles may depreciate, property prices can change, and investments may rise or fall. Use reasonable estimates and update them when appropriate.
Confusing Net Worth With Available Cash
A positive net worth does not mean you can easily afford every expense. Much of your wealth may be tied up in a home, retirement account, or investment that cannot be accessed quickly without costs or restrictions.
Use your Worth Tracker alongside a budget and cash flow review. These tools answer different questions: net worth measures your overall financial position, a budget organizes income and spending, and cash flow shows how money moves in and out over a period.
Reacting Too Quickly to Changes
Your net worth may fall because stock markets decline or property values change. It may also rise because you repay debt or save more. A Worth Tracker helps you observe the numbers, but it cannot tell you by itself which financial action is appropriate.
Review the reasons for major changes before making decisions. Avoid selling investments or taking on additional risk simply to improve a short-term figure.
Benefits and Limitations of a Worth Tracker
A Worth Tracker offers several advantages. It organizes financial information, supports goal setting, highlights debt trends, and gives you a consistent way to review progress. It can also make discussions with a qualified financial professional more productive because your records provide a clearer starting point. However, it has limitations. Your figures depend on accurate records and realistic asset valuations.
Some assets are difficult to value precisely, while private investments and property may not have an immediately available selling price. A tracker also cannot predict future returns or replace a detailed financial plan.
Treat the results as a useful snapshot rather than a complete measure of financial well-being. Your health, job security, family responsibilities, and access to cash also matter when evaluating your financial situation. For investment decisions, consider your goals, time horizon, and ability to accept losses. Investor.gov explains why these factors matter when evaluating investment risks and building an appropriate asset allocation.
Frequently Asked Questions
Q1. What Is a Worth Tracker?
A Worth Tracker is a personal finance record that lists your assets and liabilities to calculate your net worth. It helps you understand your overall financial position and monitor changes over time.
Q2. How Often Should I Update My Worth Tracker?
Many people find monthly or quarterly updates useful. You can also complete a more detailed annual review. Choose a schedule you can maintain and use consistent valuation methods.
Q3. Can I Create a Worth Tracker in Excel?
Yes. You can use Excel or Google Sheets to record assets and debts, calculate totals, and compare your net worth over time. A basic spreadsheet is often enough to get started.
Q4. What Should I Include in My Worth Tracker?
Include cash, savings, investments, retirement accounts, property, vehicles, loans, credit card balances, and other relevant assets and liabilities. Avoid counting the same asset or debt more than once.
Q5. Is a Negative Net Worth Always Bad?
No. A negative net worth means your liabilities exceed your assets at that point in time. It can occur when someone is starting a career, repaying student loans, or buying a home. Review your circumstances and make a practical plan to improve your position.
Final Thoughts
Building a clearer picture of your finances does not need to be complicated. Start by listing what you own and what you owe, calculate your net worth and record the result. Then choose a regular review schedule and use what you learn to guide your financial goals.
A Worth Tracker is most effective when you combine it with sensible budgeting, debt management, emergency savings, and informed investing decisions. It will not guarantee wealth or remove financial uncertainty, but it can help you make decisions with a better understanding of your starting point.
Begin with a simple spreadsheet today. Keep your information accurate, protect your financial data, and focus on steady progress rather than a perfect number.
3 thoughts on “How to Create a Net Worth Tracker and Why It Matters”