Introduction
Buying a home is one of the biggest financial decisions many people will ever make. Most buyers spend a lot of time thinking about the property price and the down payment. However, the purchase price is only part of the total amount you may need to spend.
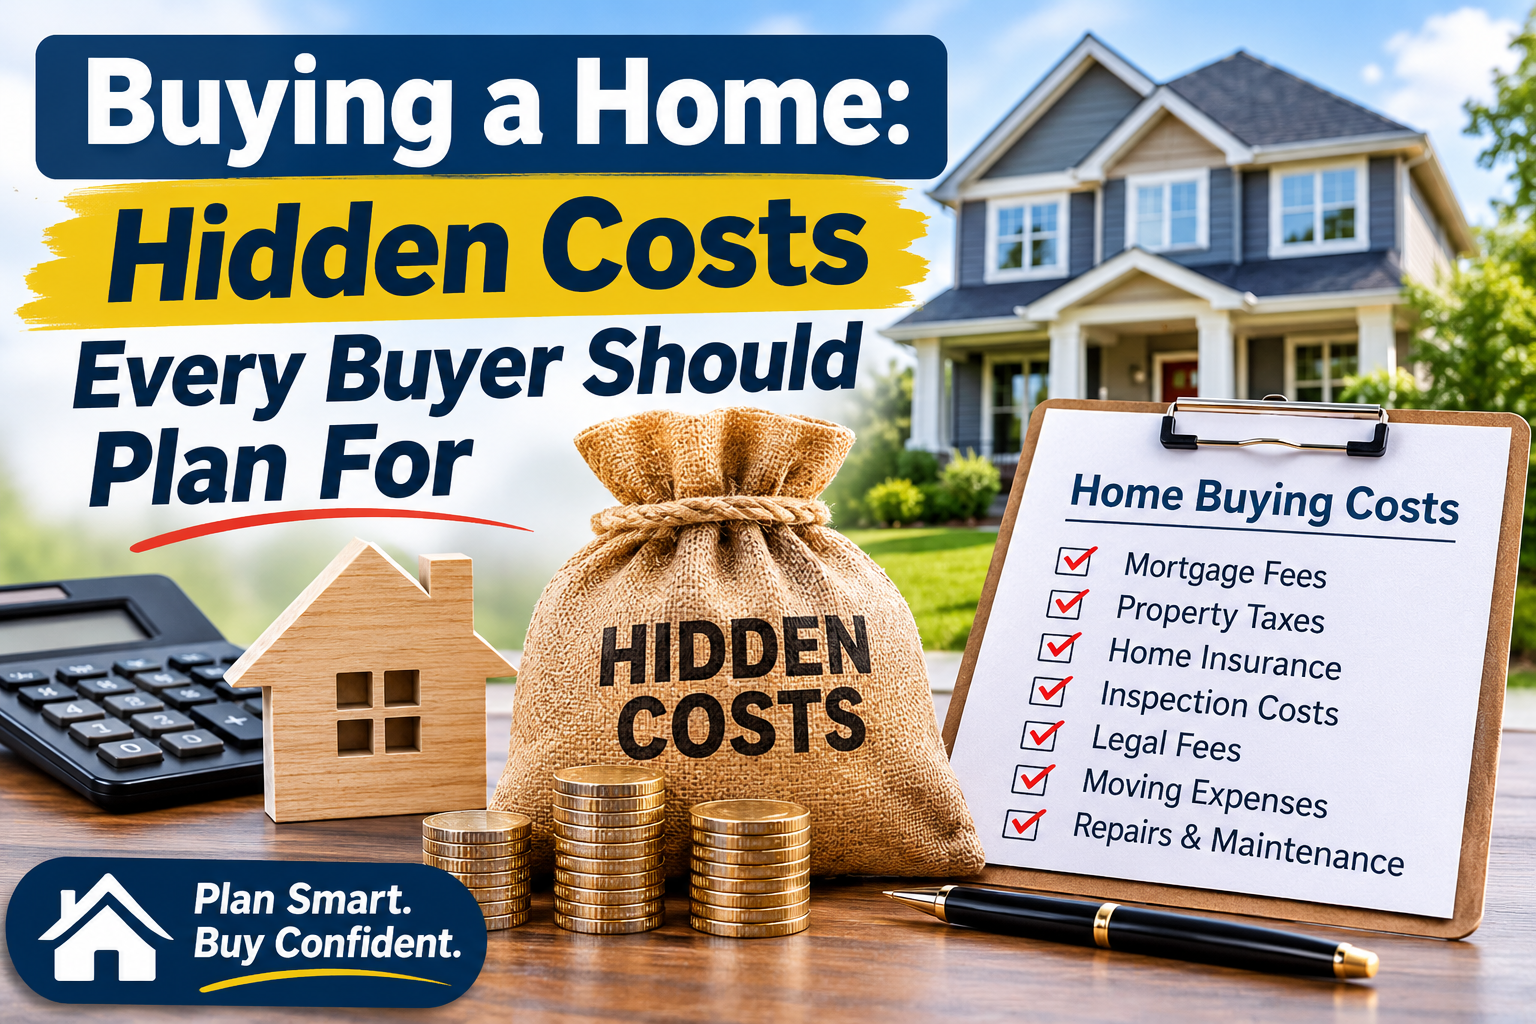
The Hidden Costs of buying a home can include mortgage fees, legal services, inspections, taxes, insurance, moving expenses, repairs and ongoing property costs. These expenses vary significantly by country, region, property type, lender and individual circumstances.
Planning for these Hidden Costs before making an offer can help you avoid financial pressure during the buying process. It can also give you a more realistic picture of what you can actually afford. This guide explains the most important Hidden Costs every home buyer should consider. Whether you are purchasing your first home or moving to another property, understanding these expenses can help you make a more informed decision.
What Are the Hidden Costs of Buying a Home?
The Hidden Costs of buying a home are expenses beyond the advertised purchase price and your initial down payment. Some must be paid before or at closing, while others begin after you become the owner.
Depending on where you live, these expenses may include:
- Mortgage application and lender fees
- Property valuation or appraisal costs
- Home inspection or survey fees
- Legal and registration costs
- Property transfer taxes
- Home insurance
- Mortgage insurance
- Moving expenses
- Repairs and maintenance
- Property taxes
- Utility deposits and connection charges
- Homeowner association or service fees
The exact Hidden Costs depend on local laws and the type of property you buy. For example, Canada.ca notes that Canadian buyers should plan for upfront closing costs in addition to the mortgage and that these can include inspections, legal fees, property tax adjustments and title insurance. It says buyers may need to budget roughly 1.5% to 4% of the purchase price for such costs. The important lesson for a global audience is simple: never assume the amount you need is limited to the property price plus your down payment.
Mortgage and Lender Fees
One of the most common Hidden Costs is the cost of arranging financing. Mortgage lenders may charge fees for services related to processing and approving a loan. The names of these charges differ between lenders and countries. Depending on your situation, you may encounter application fees, origination fees, underwriting fees, administrative charges or product fees.
Some mortgages also allow buyers to pay points or similar upfront charges in exchange for a lower interest rate. If this is worthwhile depends on how long you expect to keep the loan and the total cost of the financing.
The U.S. Consumer Financial Protection Bureau explains that mortgage-related upfront expenses can include lender charges, points, third-party services, government fees and prepaid expenses. Before choosing a mortgage, compare the full cost rather than looking only at the monthly payment.
Questions to Ask Your Lender
Ask for clear information about:
- All upfront mortgage fees
- The interest rate and annual cost of borrowing
- Whether fees can be refunded
- The cost of optional points
- Penalties or charges that may apply later
- Estimated cash required at closing
A lower monthly payment does not always mean a lower total cost.
Property Appraisal or Valuation Costs
A lender may require an appraisal or valuation before approving a mortgage. This helps determine whether the property provides sufficient value for the amount being borrowed. An appraisal is different from a detailed inspection. The purpose is generally to estimate the property’s value rather than identify every possible repair problem.
This is another expense that can become part of the Hidden Costs of purchasing a property. The person who pays can vary depending on the lender and local market. In some situations, the lender may cover the cost. In others, the buyer pays directly or indirectly. Always ask your lender whether a valuation is required and who is responsible for the charge.
Home Inspection or Property Survey Fees
A professional inspection can be one of the most valuable expenses a buyer pays. A property may look attractive during a viewing while still having expensive problems. Issues with the roof, electrical system, plumbing, structure, heating, cooling, drainage or other components may not be obvious to an untrained buyer. Inspection and survey costs are often considered Hidden Costs but they can potentially help buyers identify larger financial risks before completing a purchase.
For example, an inspection may reveal that the property needs major repairs. You may then be able to reconsider the purchase, negotiate the price, request repairs, or budget for future work. The scope of an inspection varies by country and service provider. A basic inspection may not examine every part of the property.
Do Not Confuse an Appraisal With an Inspection
This distinction is important.
An appraisal or valuation focuses mainly on the estimated value of the property.
An inspection or survey is intended to assess the condition of the property.
You may need one, both or additional specialist reports depending on your location and the property.
Legal and Professional Fees
Buying property often involves legal documents, contracts, ownership checks, registrations and other formal processes. Depending on your country, you may need to pay a lawyer, solicitor, conveyancer, notary or another qualified professional.
These Hidden Costs may include fees for:
- Reviewing contracts
- Checking ownership records
- Completing searches
- Preparing documents
- Registering the ownership transfer
- Registering the mortgage
- Handling settlement or closing
In the UK, Citizens Advice lists survey fees, valuation fees, land-related taxes, registry fees, searches, mortgage-related fees, solicitor costs and removal expenses among the additional costs buyers should consider. Professional fees can vary considerably, so obtain clear quotes before making assumptions about your total budget.
Property Transfer Taxes and Government Charges
Taxes can be among the largest Hidden Costs of buying a home. Different countries and regions use different systems. A buyer may need to pay a property transfer tax, registration tax, stamp duty, land transfer tax or another government charge.
The amount can depend on:
- The property price
- The location
- Whether it is your first home
- Whether you already own another property
- Your residency status
- Local exemptions or relief programs
For example, in England and Northern Ireland, Stamp Duty Land Tax rules and available relief depend on the property value and the buyer’s circumstances. Official GOV.UK guidance provides current thresholds and first-time buyer rules. Because tax rules can change, never rely on an old article or a general estimate when making a real purchase. Check the official authority in the location where you are buying.
Home Insurance and Mortgage Insurance
Insurance is another important part of the Hidden Costs of homeownership. Homeowners may need insurance to protect against certain types of damage or financial loss. The type and cost of coverage can depend on the property, location, lender requirements and insurance provider.
Mortgage insurance may also be required in some financing arrangements. In the United States, for example, the CFPB notes that mortgage insurance is typically required for borrowers making a down payment of less than 20%, although specific loan rules vary.
Buyers should understand:
- What coverage is required
- What coverage is optional
- What risks are excluded
- Whether premiums are paid monthly or upfront
- How insurance costs may change over time
Do not calculate affordability using only the mortgage principal and interest payment.
Prepaid Taxes, Insurance and Escrow Deposits
Some Hidden Costs appear when you reach the final stage of the purchase. Depending on your mortgage and local system, you may need to pay prepaid interest, an initial insurance premium, property tax adjustments or an initial deposit into an escrow or similar account. The CFPB explains that prepaid expenses can include interest between closing and the end of the month, advance homeowner’s insurance payments, and initial escrow deposits for future taxes and insurance.
These amounts can surprise buyers who have only focused on the down payment. Review your final loan and closing documents carefully. If an amount is significantly different from your earlier estimate, ask for an explanation before completing the transaction.
Moving and Setup Expenses
The Hidden Costs do not stop when you receive the keys. Moving into a new home can create a long list of expenses, including:
- Professional movers
- Vehicle rental
- Packing supplies
- Storage
- Travel
- Cleaning services
- New locks
- Utility connection fees
- Internet installation
- Furniture and appliances
These expenses may seem small individually but can quickly add up.
A Simple Example
Imagine a buyer has enough money for the down payment and closing costs. After moving in, they discover they also need:
- A refrigerator
- Curtains or blinds
- Basic furniture
- Internet installation
- New locks
- Moving services
The buyer could face a large additional bill during the first month. Adding a separate moving and setup budget can reduce this pressure.
Immediate Repairs and Renovations
A home does not need to be perfect to be worth buying. However, buyers should clearly separate essential repairs from optional improvements.
Essential repairs might involve:
- Roof problems
- Electrical safety issues
- Plumbing leaks
- Structural concerns
- Heating or cooling failures
- Water damage
Optional improvements might include:
- Painting
- New flooring
- Kitchen upgrades
- Landscaping
- Decorative changes
The risk is assuming that every repair can wait. A detailed inspection can help identify urgent work, but buyers should also maintain a financial buffer for unexpected problems. Repair and maintenance expenses are among the Hidden Costs that can affect affordability long after closing.
Property Taxes and Local Charges
Property taxes can create a significant ongoing cost. The amount may depend on the location, assessed property value, and local tax rules. Tax rates and assessments may also change. Some buyers focus on the monthly mortgage payment without properly considering annual property taxes.
This can make a property appear more affordable than it really is. Canada’s government home-buying guidance specifically reminds buyers to consider property taxes and other monthly housing costs when assessing affordability.
Before buying, try to understand:
- Current property tax charges
- How frequently they are paid
- Whether they are included in your mortgage payment
- Whether reassessment could change future costs
Homeowner Association and Service Fees
Some homes are part of communities or buildings with shared services. You may have to pay homeowner association fees, condominium fees, maintenance charges, service charges or similar recurring expenses.
These charges may help fund:
- Shared building maintenance
- Security
- Landscaping
- Elevators
- Common facilities
- Insurance for shared areas
- Reserve funds
However, these fees can increase over time. Before purchasing, ask about:
- Current monthly or annual charges
- Previous fee increases
- Planned major repairs
- Special assessments
- Financial reserves
- Rules affecting property use
Ignoring these Hidden Costs can create serious problems after you become the owner.
Ongoing Maintenance Costs
Every property requires maintenance. A homeowner may eventually need to repair or replace items such as:
- Roofing
- Plumbing fixtures
- Electrical systems
- Heating equipment
- Cooling systems
- Windows and doors
- Appliances
- Exterior surfaces
The timing is difficult to predict. This is why a home purchase budget should include an emergency reserve rather than using every available dollar on the down payment and closing costs. Canada’s official guidance also encourages buyers to consider repairs, maintenance, heating, cooling, yard work, utilities and other ongoing ownership expenses. These ongoing Hidden Costs are an important reason to think beyond the first day of ownership.
A Practical Hidden Costs Budget Example
The following example is illustrative only. Actual costs can be much higher or lower. Suppose a buyer is purchasing a home for $300,000.
| Expense | Example Amount |
|---|---|
| Down payment | $30,000 |
| Inspection | $500 |
| Appraisal | $600 |
| Legal and registration costs | $2,000 |
| Mortgage and lender fees | $1,500 |
| Insurance and prepaid expenses | $2,500 |
| Moving costs | $1,500 |
| Immediate repairs and setup | $3,000 |
| Estimated additional costs | $11,600 |
The example shows why buyers should not assume that a $30,000 down payment means they only need $30,000 in cash. Actual taxes and transaction costs are not included because they vary widely by location. The goal is to build a realistic Hidden Costs budget based on your own country, lender, property and circumstances.
How to Plan for Hidden Costs Before Buying
A good plan can reduce unpleasant surprises.
Create a Separate Home-Buying Budget
Do not combine everything into one general savings number. Separate your budget into:
- Down payment
- Closing costs
- Taxes and government charges
- Moving costs
- Immediate repairs
- Emergency savings
Request Written Estimates
Ask lenders and service providers for written estimates whenever possible. Compare the full cost rather than selecting a provider based on one advertised number.
Research Local Rules
The Hidden Costs in one country may be completely different from those in another. Check official government websites for current information about taxes, registration and buyer requirements.
Review the Property Carefully
Look beyond the interior design. Consider the age and condition of:
- The roof
- Heating and cooling systems
- Plumbing
- Electrical systems
- Windows
- Appliances
Keep an Emergency Buffer
Try not to use every available savings dollar during the purchase. Unexpected repairs can happen soon after moving in.
The Benefits of Planning Ahead
Planning for Hidden Costs has several benefits.
First: it gives you a more realistic idea of affordability.
Second: it can reduce the risk of taking on more debt than expected.
Third: you can compare properties based on their total cost instead of their listing price alone.
Finally: financial preparation can make the buying process less stressful.
A slightly cheaper property may not always be the better financial choice if it needs major repairs or has unusually high taxes and ongoing fees.
Common Mistakes Buyers Should Avoid
One of the biggest mistakes is focusing only on the down payment. Another is assuming the lender’s monthly mortgage estimate represents the full cost of owning the property.
Buyers should also avoid:
- Skipping appropriate inspections without understanding the risk
- Ignoring taxes and government charges
- Forgetting moving and setup expenses
- Spending all savings at closing
- Underestimating repair costs
- Ignoring association or service fees
- Choosing a mortgage based only on the lowest monthly payment
The best approach is to calculate the complete financial picture.

Frequently Asked Questions
Q1. What are the most common hidden costs when buying a home?
Common Hidden Costs include mortgage fees, inspections, appraisals, legal services, taxes, insurance, moving expenses and immediate repairs.
Q2. How much should I save for closing costs?
The amount depends on your country, lender, property price, taxes and transaction rules. In Canada, official guidance says upfront closing costs can typically range from about 1.5% to 4% of the purchase price.
Q3. Are home inspections worth the cost?
A professional inspection can help identify potential problems before you complete the purchase. Whether it is required or optional depends on the local market and your circumstances.
Q4. Do hidden costs continue after buying a home?
Yes. Ongoing Hidden Costs can include property taxes, insurance, maintenance, repairs, utilities, and homeowner or service fees.
Q5. How can I avoid unexpected home-buying expenses?
Research local requirements, request written estimates, review closing documents carefully, inspect the property appropriately and maintain an emergency financial buffer.
Final Thoughts
Buying a home can be exciting, but the purchase price is only one part of the financial commitment. The Hidden Costs can include mortgage fees, inspections, legal services, taxes, insurance, moving expenses, repairs, maintenance and ongoing property charges.
The exact Hidden Costs will depend on where you buy and the type of home you choose. For that reason, buyers should use current information from lenders, government authorities, qualified professionals and local service providers. Before making an offer, build a complete budget that includes the down payment and all expected expenses. Keep extra savings for unexpected repairs and carefully review every estimate you receive.
Understanding the Hidden Costs before buying can help you make a more confident decision and reduce financial surprises after you become a homeowner.
Image Alt Text: Home buyer reviewing hidden costs, mortgage fees, taxes, and property expenses before purchasing a house
3 thoughts on “Buying a Home: Hidden Costs Every Buyer Should Plan For”